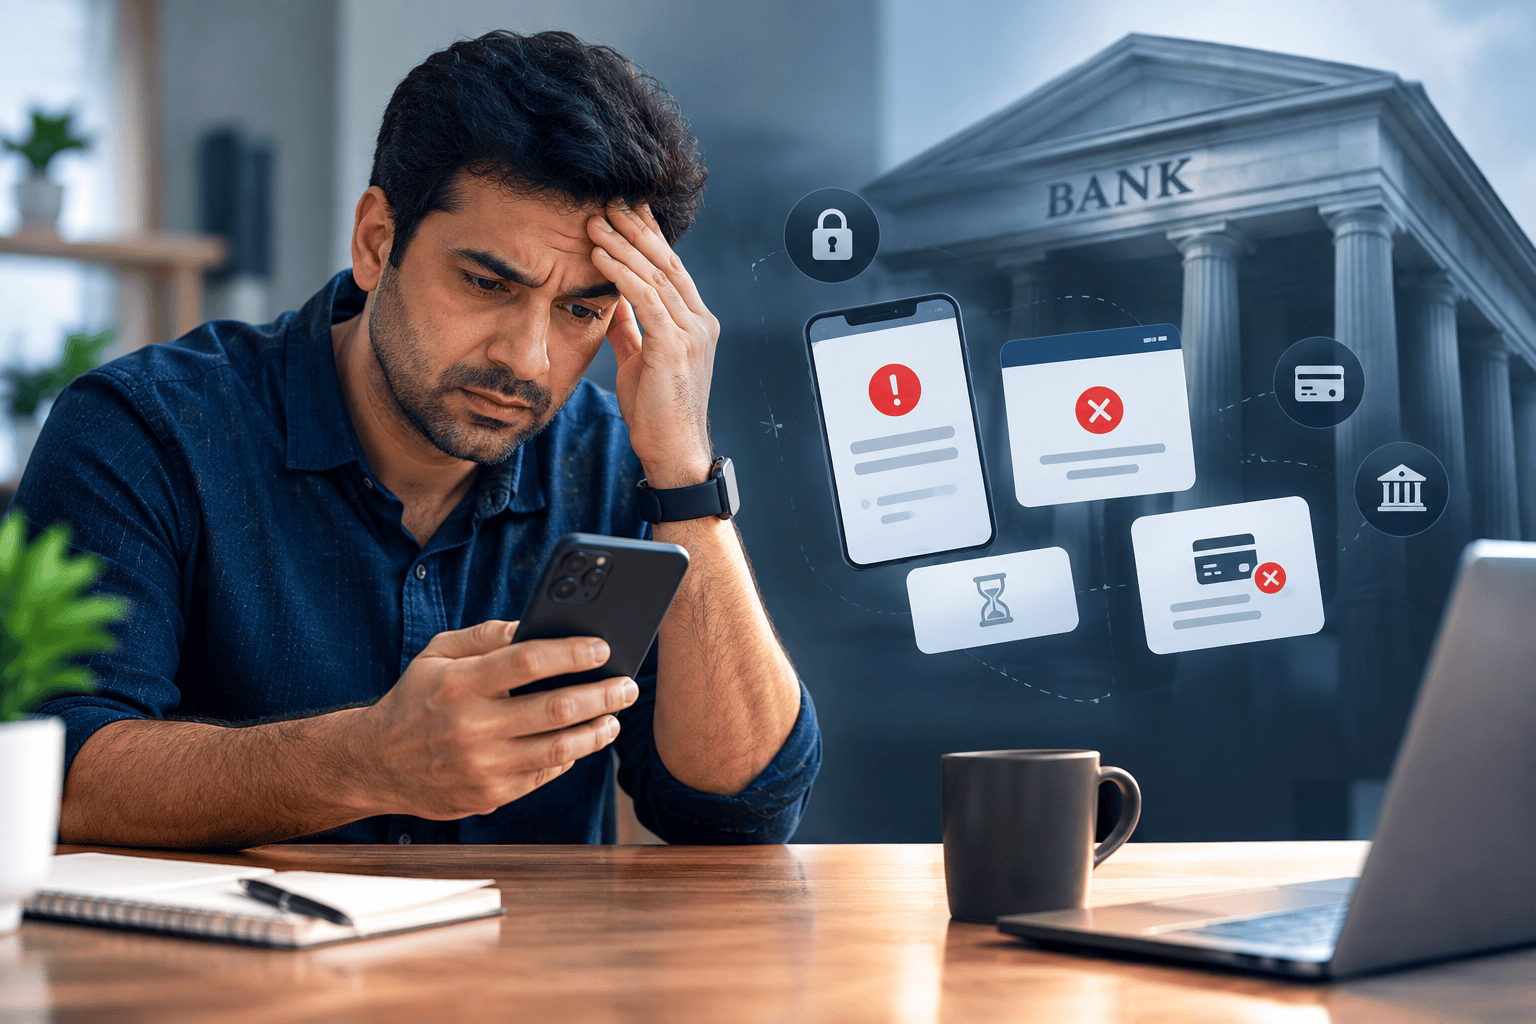
Try this the next time you're at a family dinner. Ask everyone at the table if they've ever gotten annoyed enough at their bank's app to just... give up on whatever they were trying to do. Close a tab mid-application. Abandon a transfer. Walk away from opening a new account because it asked for one more document than they had patience for.
I'd bet almost every hand goes up.
That small, everyday moment of frustration — the one nobody reports, nobody complains about, and nobody puts in a support ticket — is quietly one of the most expensive problems in banking right now. Not fraud. Not interest rates. Not even competition from neobanks, exactly. It's friction. Plain old bad user experience. And in 2026, the cost of poor UX in banking has become a number too large for any CFO to keep ignoring.
I wanted to dig into what that number looks like, because "bad UX is bad for business" is the kind of line that gets thrown around in every design deck without much behind it. So let's get specific.
Why "Cost of Poor UX in Banking" Isn't Just a Buzzword Anymore
Here's the uncomfortable part. Digital banking is doing better than ever on the surface. Mobile banking activation has climbed past 80% at most institutions. More people than ever are opening accounts online instead of walking into a branch. On paper, digital transformation looks like a success story.
But dig one layer deeper, and the story flips. For every account a bank successfully opens online, it's losing more than three applicants somewhere along the way. Industry-wide, digital account abandonment sits somewhere between half and three-quarters of everyone who starts the process. Read that again — most banks are losing the majority of the people who show interest before those people ever become customers.
That's not a UX footnote. That's the whole funnel leaking.
And it's not only the new customers walking away mid-application. The people who already have an account with you aren't immune either. A confusing login screen, a clunky transfer flow, a support experience that goes nowhere — these are the exact moments that push existing customers toward what a lot of banking analysts now call "silent churn." Nobody closes the account. The direct deposit keeps landing. Everything looks fine on the dashboard. Meanwhile, the customer has quietly started using a different app for the things that actually matter to them, and your institution just becomes the place their paycheck technically lands.
That's the real cost of poor UX in banking — it doesn't announce itself. It just shows up later as a number nobody can quite explain.
Where the Money Actually Disappears
Let's walk through where this shows up, because it's not one single leak — it's several, and they compound.
Onboarding is the biggest one. Every extra form field, every blurry ID re-upload, every "we'll email you in 3-5 business days" moment is a reason for someone to just... not finish. A huge share of digital account-opening abandonment traces directly back to identity verification steps that feel more analog than digital — the kind of process that makes someone feel like they've wandered into 2014.
Authentication is the quiet, recurring one. People open their banking app several times a week. Every login loop, every forgotten-password dead end, every extra security step chips away at that relationship a little more each time. It sounds small until you multiply it by every login, every week, for every customer.
Mobile performance matters more than most banks think. If a page takes more than a few seconds to load on someone's phone, a huge chunk of visitors are simply gone. Not annoyed but staying. Gone. And with mobile now being the primary way most people interact with their bank, a slow or clunky mobile experience isn't a minor UX gap anymore — it's the front door of the business, and it's sticking.
Fragmented systems make it worse behind the scenes too. When core banking systems, call centres, and digital platforms don't talk to each other properly, customers feel it as inconsistency — being asked to repeat information, getting different answers from different channels — and banks feel it as higher operating costs on top of the lost revenue. It's a double hit.
Putting an Actual Number on It
I know "millions in lost revenue" sounds like the kind of thing every industry report says about every problem. So let's make it concrete with a simple way to think about it.
Picture a mid-sized bank running 50,000 digital account applications a year. If half of those get abandoned somewhere in the process, and each funded account is worth even a modest amount in lifetime deposits and fees, you're not talking about a rounding error. You're talking about millions of dollars in value that never had a chance to materialize — plus all the money already spent on marketing to get those applicants in the door in the first place. That spend doesn't come back just because the customer left before converting.
Now layer on churn. Banks in the U.S. are seeing annual customer churn somewhere in the 12–15% range, and switching behavior is reportedly at its highest point in a decade. Acquiring a replacement customer costs several times more than keeping the one you already had. So every customer lost to a bad experience isn't just a loss — it's a loss plus a bill for whoever gets recruited to replace them.
Add it all up — abandoned applications, wasted acquisition spend, and preventable churn — and you start to see why "the cost of poor UX in banking" deserves a seat at the boardroom table instead of staying a line item in the design team's budget request.
The Flip Side: What Good UX Is Actually Worth
Here's the part that should make this easier to sell internally, not harder.
The gap between an average bank and a best-in-class one, on the same onboarding requirements and the same regulations, is enormous. Where the average institution might convert roughly a quarter of its applicants, the best ones are converting the large majority — sometimes five times better. Same rules. Same compliance burden. Wildly different outcomes. That tells you the problem was never really about regulation. It was about execution.
There's a stat that gets repeated a lot in design circles — that every dollar spent on UX returns something like a hundred dollars back. It sounds almost too good, and I'd take the exact multiple with a grain of salt because it varies wildly by product and starting point. But directionally, the research keeps pointing the same way: small improvements in activation and onboarding translate into outsized gains in long-term revenue. A modest lift in how many customers successfully activate their account has been linked to a much larger lift in long-term revenue for that product. That's not a rounding effect either.
And the businesses actually measuring their customer experience as a revenue driver — not just a satisfaction score sitting in a slide deck — are far more likely to be the ones posting above-average growth.
So What Should a Bank Actually Do About This?
If I had to boil it down to three things worth fixing first:
Fix the account-opening funnel before anything else. It's the single biggest, most measurable leak, and it's the one with the clearest fix — save-and-resume flows, fewer required fields, and identity verification that doesn't feel like a chore.
Stop measuring churn only by closed accounts. Silent churn doesn't show up until it's too late. If your only churn signal is someone formally shutting their account, you're finding out about the problem after the customer has already mentally left.
Treat the first couple of days after signup like it matters — because it does. Customers who don't complete a meaningful first action shortly after opening an account are far less likely to ever come back and try again. That early window is where the relationship is either built or lost.
The Bottom Line
Banking isn't losing customers because people suddenly stopped needing bank accounts. It's losing them one small frustration at a time — a form that felt too long, a login that failed twice, a support call that went in circles. None of those moments shows up as a single dramatic failure. They show up as a slow leak that only becomes visible once someone finally adds up the number.
The cost of poor UX in banking isn't hypothetical anymore. It's sitting in abandoned applications, in silent churn, in acquisition budgets spent on customers who never actually arrived. The institutions figuring this out aren't spending more money to grow — they're just losing less of what they already have. And in a business where trust and convenience decide where money lives, that difference adds up fast.

 MAKE
